• As economic development celebrates its 100th anniversary, the field is shifting toward business creation and retention from costlier attraction.
• Less money sooner helps more. Accelerators, incubators, and public startup programs serve as the strongest correlates for expanding knowledge-intensive firms. But quality matters.
• Entrepreneurial “ecosystems” require shared communications strategies to coordinate distributed networks.
The man had lost patience with me.
Most of the site-selection consultant’s time was spent on the very serious work of modeling construction costs to place established businesses in new offices. He once showed me an elaborate spreadsheet of how different programs and incentives made any given expansion profitable enough for everyone with a direct stake — the expanding company, the property developer, the consultant and the city, because it could expect to add a few dozen tax-paying workers.
A decade or so ago, I was failing to convince him to sponsor an event for high-growth entrepreneurs and technologists that Technical.ly was hosting.
“Tech people just want us to pay for their parties,” he said.
A whole generation of pro-entrepreneurship advocates who call themselves “ecosystem builders” believe state and local economic development strategies under-invest in encouraging homegrown startup growth. Back then, I knew we were doing something more important than “parties,” but I didn’t yet know how to argue it. I do now.
This is the second in a three-part series on how place-based economic development is changing, timed to the field’s 100th anniversary at the annual conference of its primary membership body, the International Economic Development Council.
Part one of this series argued that business attraction’s dominant lever — subsidizing expansions and relocations from established firms — is costly and ineffective. Each additional job bought that way can run 3 to 5 times what it costs to grow a local firm, and American economic developers spend eight times as much on the expensive option. Why hasn’t the field adapted? Because the research is newly mounting, and whole careers and organizations were built the old way. Change will not come easily. Part three will look at what is still unknown and unfinished in this transformation.
But first, as growth-hungry state and local economic development strategies prioritize creation and retention alongside business attraction, what do we actually know works in supporting entrepreneurial growth?
The insurgency
After the Great Recession, confidence in financial engineering collapsed and a generation of local organizers went looking for something else to build. In many places, that dissatisfaction fused with Silicon Valley cool, corporate-expat GenXers and local-loving millennials, most of whom held a reverence for small business. They borrowed a biological metaphor and called it “entrepreneurial ecosystem building,” the practice of stitching together differently sized and loosely affiliated efforts into something resembling a strategy. Books were written. Dell Gines, a former Federal Reserve advisor, the outgoing chief innovation officer at IEDC and author of one of them, calls it the fourth wave of economic development.
“Historically, economic development has been seen in isolation from a lot of the … entrepreneurship work that we do,” Gines said at our Builders Conference last year. “That’s the foundation of the next evolution of effective economic development: looking at how people connect together, how people understand each other, and then they mobilize capital, energy, talent and resources to produce productive gain for everybody.”
In most places, traditional economic development sneered at these self-organized coalitions of inventors and researchers, business creators and software developers who traded drab chamber networking affairs for workshops laden with startup lingo and beer-soaked social gatherings.
To those in business recruiting, it looked like a faddish novelty. One of Philadelphia’s most influential economic developers once explained why he didn’t take startup engagement seriously: “If you take all the tech startups together, I’m not sure they’d fill 100,000 square feet of commercial real estate.” (The Technical.ly newsroom then made sport of proving him wrong by counting office openings.)
Meanwhile the field stayed locked in a century-old arms race swapping tax subsidies for established businesses. Its cultural high-water mark may be the 2017 Amazon HQ2 bonanza, when a now-multi-trillion-dollar company flirted with 238 regional coalitions to extract the sweetest package from Arlington, VA, for a campus whose second phase is still on hold.
Fortunately for Virginians the Amazon HQ2 deal was rare. Their state is among the stingiest in the country, and good thing: Influential research has shown essentially no correlation between tax incentives and economic outcomes.
Worse, according to a new Technical.ly analysis, the states that offer the most in business incentives have the fewest homegrown companies built to grow. The Upjohn Institute measures the five standard tools — tax credits for job creation, investment and R&D, property tax abatements and customized job training — against the value the subsidized firms add. Nationally it comes to about $1.42 for every $100 of value added, triple what it was in 1990.
We paired that Upjohn incentive data with MIT’s Startup Cartography Project, which scores every new firm on its odds of reaching an IPO or major acquisition, and counted those firms per million residents. New Mexico, Tennessee and Iowa buy the most and produce the fewest. Nevada, Colorado, California and Massachusetts buy the least and produce the most.
To make this more concrete, take Louisiana, which spends more on business incentives than the 33-state average. If the relationship between chasing established businesses and supporting new ones held, closing that gap is worth roughly five more high-growth companies a year for Louisiana, or close to 50 over a decade.
Those represent hundreds, or even thousands, of the most in-demand homegrown jobs and other knock-on effects in a state confronting population loss. Louisiana is trying to address this — starting with federal SSBCI allocations.
Nexus Louisiana (which partially underwrites our reporting) has also set a goal of 1,000 net new high-growth startups over a decade. CEO Tony Zanders argues the case by pointing at Meta’s Hyperion data center in Richland Parish, the biggest incentive deal in Louisiana history. “You can’t have $30 billion in economic tax-incentivized impact without, 20 years ago, this very small seedling of a company starting,” he said, meaning Facebook.
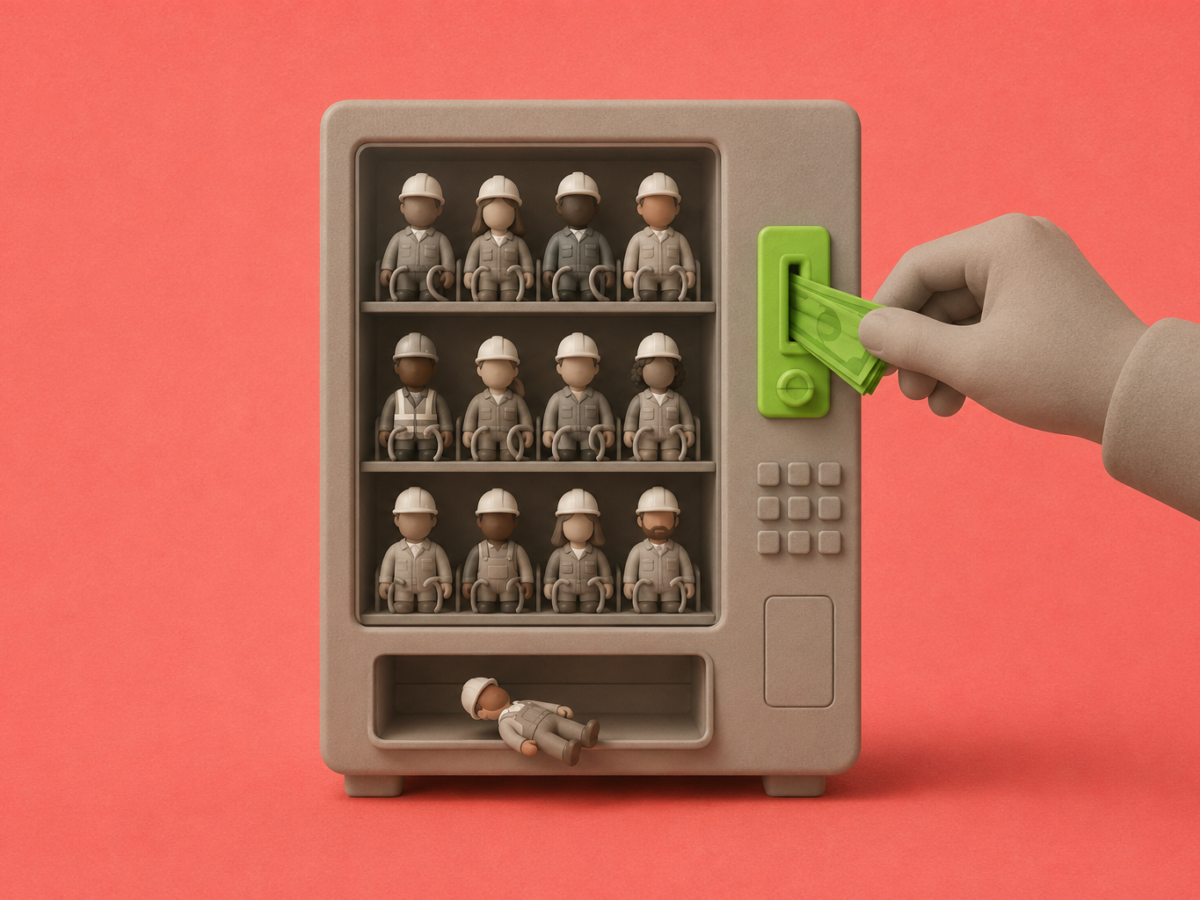

The obvious objection is that this runs backward, that the states without homegrown companies are the ones forced to go shopping for someone else’s. The data doesn’t support it. States with weak startup activity in 1990 were no likelier than anyone else to raise incentive spending over the next 25 years. The states that increased it most actually saw their startup activity grow least.
This doesn’t prove incentives crowd out homegrown growth. I’m a journalist, not an academic, and startup activity is stubbornly persistent, while prosperous places stay prosperous. But the simplest competing explanation doesn’t survive, and the one study to test the question causally found the same shape: State research credits raised both the number and the quality of new firms, while recruitment-focused investment tax credits tracked a falling rate of growth-oriented startup formation.
Practitioners have been circling this for years. Back in 2009 one insider said companies that entered Pennsylvania by acquiring an existing firm often stayed, while those lured from elsewhere didn’t. “If you give incentive grants, they stay as long as the grant.”
In contrast, focusing on accelerating homegrown entrepreneurs appears cheaper and more effective. It is the start of a local economy, after all, and rigorous evidence exists about what works best.
What the research rules in
Three findings are solid enough to act on now, and all three cut against how the field spends.
1) Small and early beats large and late
An analysis of Department of Energy research grants by Sabrina Howell, now of Harvard, showed that an early award of roughly $150,000 doubles the probability that a firm later raises venture capital, with large positive effects on patenting and revenue. The effect isn’t the prestige of winning. The money funds a prototype, which reduces what an investor doesn’t know.
A larger follow-on award of approximately $1 million showed much weaker effects. More money later did less than less money earlier.
2) Money and physical space alone don’t help, but structured training does
Among entrepreneurs evaluated by Start-Up Chile, cash grants and coworking space had no detectable effect on fundraising, scale or survival.
Cash paired with structured entrepreneurship schooling, on the other hand, increased the probability of raising capital and average employee count. A randomized trial of subsidized consulting in Puebla, Mexico and research on business training in Tanzania said something similar.
A World Bank analysis found many entrepreneur programs underperform, which anyone who has sat through a small-business seminar with stale coffee and worse suits already knows. Entrepreneurship really can be taught but quality counts. Put entrepreneurs with others who have real-world experience, especially customer development, reminds GrowthX CEO Andrew Goldner, who does such training.
“Startup activity and startup growth are not the same thing,” Goldner said: Founders “are learning to pitch without learning to sell.”
3) Accelerators appear to change places, not just companies
Well-run, intensive, cohort-based programs — called accelerators ever since Y Combinator established the form 20 years ago — are associated with increases in regional seed and early-stage venture activity, including for companies that never went through the program.
Plenty of now-ubiquitous entrepreneur-support programs have gotten a bad rap among organizers because they were overstretched, reminds Heidi Knoblauch, who chaired Troy, New York’s industrial development agency and now runs Homefield, which sells impact-tracking software to economic development organizations. (Her firm has underwritten this newsletter.)
Pitch competitions started as a way to share an idea and became reality TV-style theater. Likewise, underperforming accelerators bloated what has demonstrated success.
“We’re applying that particular tool to too many companies,” she said.
Economic developers even have ways to identify the firms most likely to grow fastest (though entrepreneurship advocate Victor Hwang cautions against pre-judging entrepreneurs too aggressively).
Two academics analyzed nearly 28 million business registrations across 32 states to build a measure of entrepreneurial quality out of public records. The model they built predicted almost 70% of the companies that later went public or sold at high value.
According to their analysis, firms registered in Delaware instead of their home state (which many are) were 18 times likelier to grow. Ones with a patent, 23 times likelier. Doing both the patent and the Delaware registration, 84 times as likely. Name the company after yourself and your odds of growth fall by 70%.
None of that is advice. Reincorporating in Delaware doesn’t make a company grow. The signals work because they cost something, and what they reveal is intent.
Any economic development organization more serious about growth than about preserving its existing strategy could start here.
What research says about ecosystem building
In 2024 a separate team of researchers tested a framework that split an “entrepreneurial ecosystem” into 10 elements by analyzing across 257 studies and 2.2 million observations.
Six of the 10 elements meaningfully influence a place’s general business creation, including capital access, college degrees and self-employment levels.
Narrow it to only the firms that grow and one element leaps from laggard to leader. Incubators, accelerators and government startup programs do nothing measurable for the raw count of new businesses — yet become the strongest significant correlate of high-growth, knowledge-intensive startups.
Network building is poorly researched, but a reasonable proxy is a study of a grant program in St. Louis, which found two things firm-level metrics miss. The money produced a cohort of founders who learned from one another, and it pushed the region’s support organizations into coordinating with each other. The conclusion was methodological: Evaluating entrepreneurship strategy should look past individual firm performance to whether the broader network became more integrated.
Then how do you coordinate the inherent chaos of a distributed network? Communications is the overlooked, commonsense part. Residents can’t use programs they don’t know about, and they’re less likely to risk it all without seeing a neighbor go first. A Technical.ly analysis showed a dedicated, independent “storytelling strategy” leads to faster connections, more follow-on coverage and higher startup valuations.
Ecosystems are built partly out of the stories a region tells about itself, argues University of Tennessee at Chattanooga professor Philip Roundy. Those distributed stories are self-improving by competing with each other.
Looking back at my tussle with that site-selection consultant in the 2010s, I am sympathetic to his exasperation. He sold boxes my tribe did not fit into.
Traditional economic development is most comfortable with the wide rivers, shipping channels and ports of an economy’s establishment. In contrast, entrepreneurship is an economy’s wellspring, and a gusher can surprise. Anyone with whitewater rafting experience knows you never control the current.
No, parties alone don’t move an economy. But every community forms around relationships and stories. Parties help. Once blessed with enough daring business starters willing to brave the rocky waters of the American economy, a growing body of research demonstrates what to do next.
All that comes next is a bit of patience.