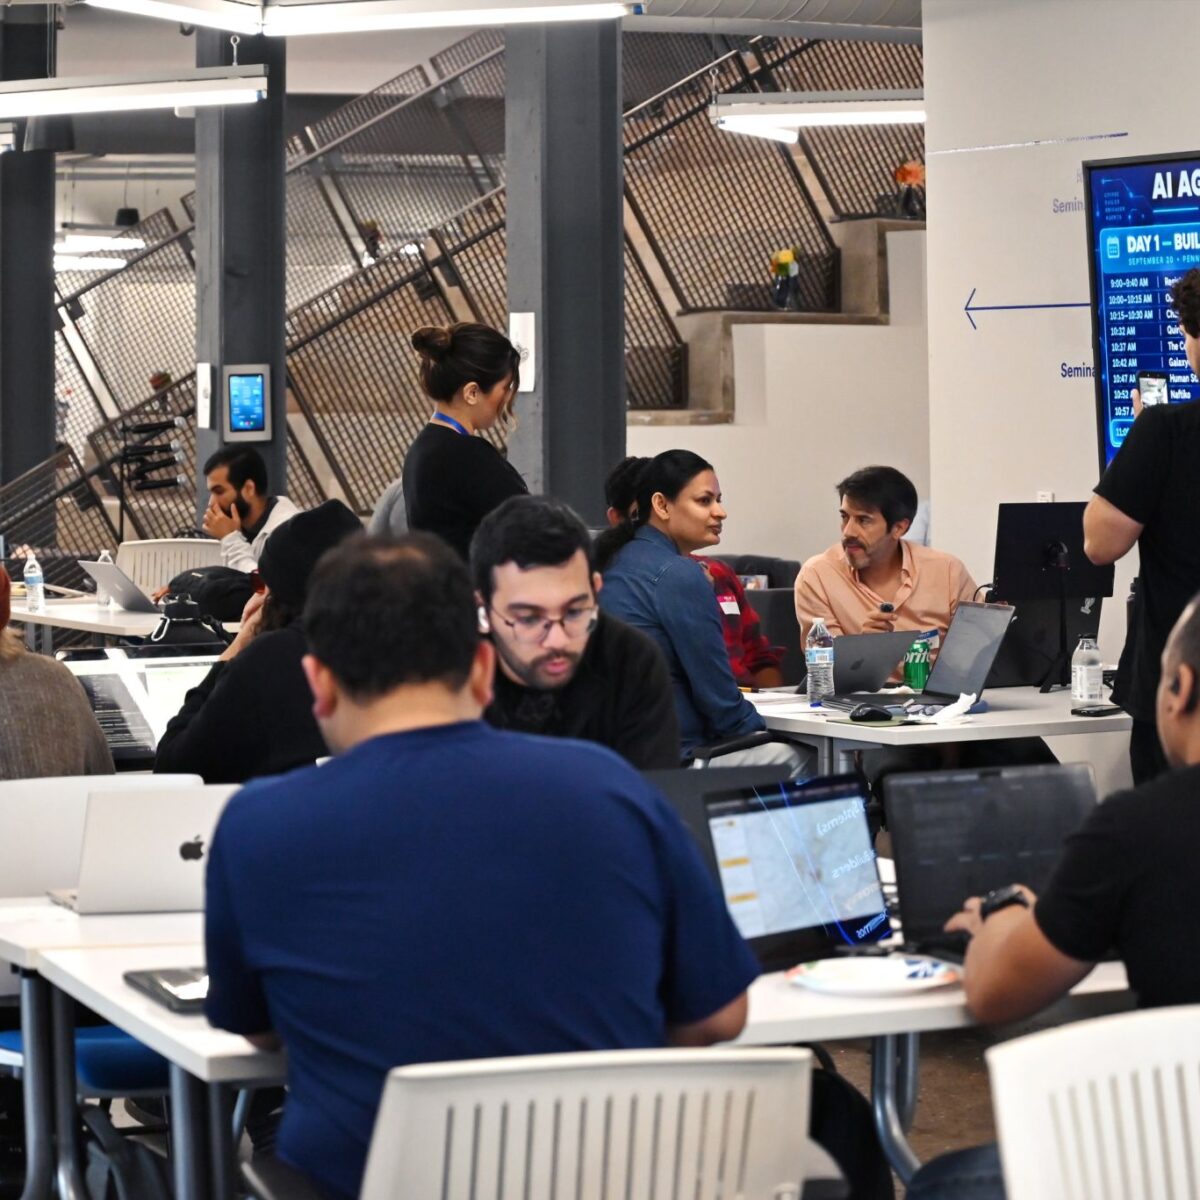
For years, cities asked: how do we create more startups here?
Most rising startup cities have one advantage they don’t use nearly well enough: local institutions with real problems.
That was the right question for a while. It led to accelerators, seed funds, university programs, meetups, coworking spaces and more people willing to call themselves entrepreneurs in places where that once felt unusual.
But the question has changed. It’s no longer enough to ask how a region creates more startups. The question now is: how does a region help more of its startups become real companies?
By real, I don’t mean venture-backed, accepted into an accelerator, or invited to pitch on a stage. I mean customers buy what the company sells, keep buying it, and the company eventually creates enough economic value to support jobs, wages and local wealth.
This is the commercialization gap. Increasingly, it’s not just a founder problem. It’s an economic development problem.
The first playbook worked
The old startup playbook is easy to question now: pitch nights, demo days, ecosystem maps and innovation districts. But much of that work was a rational response to what regional leaders saw.
Silicon Valley had density: founders, operators, capital and supporting talent moving through the same network. So cities tried to recreate some of those conditions. They funded accelerators, created networks and put experienced people closer to founders.
That logic wasn’t wrong. Density, proximity and trust matter. Steve Case’s Rise of the Rest helped popularize the idea that entrepreneurship was not confined to Silicon Valley. For a while, the important work was helping people begin.
Kauffman Foundation research has long shown why startups matter, including finding that new firms add about 3 million jobs in their first year.
The instinct was right. But there was an assumption buried in the playbook: if a region could produce more startups, enough would become growth companies.
That assumption is now looking weaker.
Activity is not growth
A region can have plenty of startup activity and still not have enough startup growth. It can have applications, accelerators, mentors and demo days, while still producing too few companies that reach repeatable revenue.
Counting founders is easy. Counting whether revenue quality improved is harder. Counting capital raised is easy. Counting whether a company learned that its first buyer was wrong, that a pilot had no path to budget, or that a polite conversation was never a real sales opportunity is hard.
Those harder questions matter more now because AI is forcing the issue. The pre-AI playbook was built for a world where getting started was one of the hardest things: finding technical talent, affording it and getting a prototype into the world before the money ran out.
A founder no longer needs the same team, budget, or time just to get something built.
Stanford’s 2025 AI Index found that 78% of organizations reported using AI in 2024, up from 55% the year before. A controlled GitHub Copilot study found developers completed a coding task 55.8% faster with the tool.
Some AI hype is silly. Some demos are misleading. Some code is bad. Still, it’s easier than it used to be for a small team to build a functioning product.
That’s good. But if more founders can build something, the harder work is helping them understand a real customer well enough to become a business. AI can help around the edges. It can’t make a buyer care.
The new failure mode looks like progress.
From the outside, a company can look like it’s moving. The deck is sharper and the demo cleaner. There are pilots “in discussion” and partners “interested.”
None of that is fake. It’s just not the same as market progress. The danger is that ecosystems can mistake that motion for momentum, and founders can spend months getting better at the story without getting closer to the customer.
Founders adapt to what their environment rewards. If the ecosystem rewards fundraising fluency, founders learn to sound fundable. If it rewards pitch polish, they get polished. If it rewards ambition, they make the story bigger.
But buyers don’t buy ambition. They buy relief from a real, urgent problem.
Local customers are the underused asset
Most rising startup cities have one advantage they don’t use nearly well enough: local institutions with real problems.
Hospitals, manufacturers, banks, logistics companies, schools and public agencies have budgets, complexity and operational pain. These organizations often sponsor events, sit on panels and judge pitch competitions. All good, just not enough.
The more useful role is the customer, or at least an honest potential customer. Startups shouldn’t win business because they’re local.
What helps more is getting founders in front of real customers and letting them learn what it would take to earn the business. But not through random introductions. The startup has to do some work first: what specific problem it solves, who owns it, which companies feel it the most, and why that customer would care now.
Buffalo offers a great example. The 43North Foundation’s Ambassador Network intentionally connects established Buffalo businesses to the region’s innovation economy, including as early adopters and paying customers.
The next regional advantage
More startup activity, by itself, will not get us there. As building gets cheaper, more companies will look credible earlier.
The regions that make progress will still support builders. But they’ll also get much more serious about everything that has to happen after something is built. That includes helping founders reach real customers, but it also means making it easier for large institutions to buy from young companies, closing the capital gap between pilot and scale, navigating regulation in sectors like health care, energy and government, and developing the operating talent companies need once demand starts to show up.
Go-to-market and sales support matter, but they are not the whole answer. A company also needs buyers who can act, procurement paths that do not quietly exclude startups, investors who understand the stage, institutions willing to test responsibly, and a local labor market that can help the company grow.
That may be the next dividing line among startup cities: how much activity they help turn into companies with real customers, real revenue and a real chance to grow where they started.